FAGE yoghurt: unexpected success and a struggle for survival
A marketing strategy book from 2015 led me to an FMCG case about FAGE Greek yoghurt in the US. I then asked ChatGPT about the company’s situation and its initiatives since 2015 to turn things around. The discussion offered useful insights for Belgian businesses and prompted reflection on entrepreneurial courage and good versus poor marketing strategy. Judge for yourself.

Yesterday, while reading a marketing strategy book from 2015 in my spare time, I came across an FMCG case about FAGE Greek yoghurt in the US. Curious, I asked ChatGPT about the company's situation and the business initiatives its management had taken since 2015 to turn things around. The discussion offered marketing strategy insights that Belgian businesses would do well to consider. It also prompted reflection on entrepreneurial courage, bold moves and good versus poor marketing strategy. Judge for yourself!
First, the case reproduced from the book in the original article:
FAGE yoghurt: unexpected success and a struggle for survival
George Nakos, Professor of Marketing, Clayton State University, Morrow, GA, USA
Robert Moussetis, Professor of International Business, North Central College, Naperville, IL, USA
David Furman, Professor of Marketing, Clayton State University, Morrow, GA, USA
Summary
This case examines Greek yoghurt company FAGE's entry into the US market. In a pioneering move, it introduced thick Greek yoghurt to the United States. Initially targeting a small niche, the product quickly became widely popular.
Growing sales attracted new competitors. FAGE's share declined and it became a smaller player in a crowded market. Its challenge was to choose a strategy to defend its US share and recover lost ground.
Introduction
FAGE began as a small dairy shop selling yoghurt and other milk products in a neighbourhood of Athens, Greece. Athanasios Filippou, grandfather of the owners described in the case, founded it in 1926 (FAGE Greece website, undated).
Yoghurt was already popular in Greece, where numerous small dairy shops made it daily. The original FAGE shop resembled many others selling dairy products in the Greek market.
During the 1950s and early 1960s, amid Greece's rapid post-war economic growth, the company invested in a wholesale yoghurt network. It was the first of its kind in Athens, previously served by small artisanal yoghurt shops.
In the 1970s, the company consolidated its Greek position and expanded into foreign markets. Innovative approaches and a strong commitment to quality helped it grow into a business operating in several countries.
At the time described in the case, the company had production facilities in the US, Greece and Luxembourg and sold products in 40 countries.
International relocation
In 2014, the company moved its headquarters from Athens to Strassen, Luxembourg. This unusual relocation reflected its increasingly international character and Greece's financial crisis.
Greek companies faced difficulties securing favourable financing. FAGE believed headquarters in an advanced, stable economy would improve its access to international capital.
In 2019, Greece represented only 15.3% of total revenue, the US approximately 45% and other countries 40% (MarketLine, 2020b).
These figures demonstrate the success of international expansion. During its first 70 years, nearly all production was sold domestically; subsequently almost 85% was sold across foreign markets.
Expansion into the United States
FAGE first exported to the US in 1998, targeting Greek Americans and other communities familiar with thick, creamy Greek yoghurt.
In 2000, it established a wholly owned subsidiary, FAGE USA Corporation, to import and distribute products. Sales grew rapidly as they became popular with a wider American audience.
By 2004, FAGE was well on its way to expanding its US position.
FAGE yoghurt: unexpected success and a struggle for survival
US expansion
The company sold 2,000 tonnes of imported yoghurt and identified an opportunity for US production. In February 2004, it decided to invest in a modern dairy facility in Johnstown, New York.
Johnstown offered proximity to dairy farms and a large consumer population in northeastern metropolitan areas (Labs, 2009). The plant cost $148.3 million, a major investment for a relatively small family company (FAGE USA website, undated).
Between 2015 and 2019, another $350 million was invested in expanding the US facility (MarketLine, 2020b). When the plant opened in 2008, it employed 120 full-time staff.
Initially sold through ethnic markets, speciality shops and health-food stores, FAGE products subsequently reached major supermarket chains.
Marketing strategy and growth
FAGE's US promotional campaign was creative and successful. Advertising Age recognised it as the product that best lived up to its advertising claims (Iezzi, 2008) following its 2007 campaign. The publication praised its print and outdoor advertising for making an impression and generating consumer interest.
Sales subsequently rose quickly, establishing creamy Greek yoghurt as a mainstream supermarket product.
Total Greek yoghurt sales rose from $33.3 million in 2007 to $469 million in 2010, reaching $3.7 billion in 2019 (Statista, 2021).
Annual growth of 48% over twelve years was exceptional in food. While most US grocery sales stagnated and consumption of other dairy products declined, Greek yoghurt's popularity exploded.
Losing the lead as competition grows
FAGE was the first company to market Greek yoghurt in the US, but quickly lost its first-mover advantage.
Newcomer Chobani, with more aggressive marketing and competitive prices, became market leader. Sales through supermarkets, drugstores and other outlets rose from $257.3 million in 2010 to approximately $2 billion in 2019.
FAGE's sales, by contrast, rose from $141.7 million to just $210 million over the same period. It failed to maintain or expand market share despite sales growth.
Its 25% share in 2010 (Elliott, 2011) fell to 5.6% by 2019.
It dropped from second to fourth place, behind the Greek yoghurt offerings of General Mills and French food company Dannon (Statista, 2021).
Unexpected success
FAGE's success in creating a new US product category was unusual and unexpected.
Many observers were surprised. Bill Patterson, an analyst at Mintel, commented:
“It wasn't as though there was a clear marketing campaign. Greek yoghurt simply appeared. It was really consumer-driven, which is quite unusual.” (Schultz and Parekh, 2011; translated from the Dutch article).
The category grew from less than 1% of the US yoghurt market in 2005 to 12% in 2010 and 45% in 2019 (Statista, 2021).
Figures: Greek yoghurt's growth performance (Table 1)
Total Greek yoghurt sales, 2019: $3.7 billion
Total Greek yoghurt sales, 2010: $469 million
Total Greek yoghurt sales, 2007: $33.3 million
Greek yoghurt's share of yoghurt sales, 2019: 45%
Adults who eat yoghurt: 58%
Chobani market share, 2019: 54%
FAGE market share, 2019: 5.3%
Average monthly yoghurt consumption occasions per American: 7.5
(Sources: Mintel, Statista, Schultz & Parekh, Manifava)
Why did Greek yoghurt become popular in the US?
It probably succeeded because health-conscious consumers wanted products with few ingredients.
Straining yoghurt through cloth removes much of its liquid, creating a thicker product described in the source case as having:
• Twice the protein of regular yoghurt (Elliott, 2011).
• Half the carbohydrates.
• 99.9% lactose-free composition, making it easier to digest.
Greek yoghurt is often described as “everyone's dream: fat-free yoghurt with the rich flavour of sour cream” (Stilson, 2006; translated from the Dutch article).
Its growth aligns with other US dietary trends: the Mediterranean lifestyle, demand for organic food and interest in functional foods.
This created a loyal following among:
• Athletes seeking protein-rich foods.
• People following a diet.
• Cooks and food enthusiasts.
Earlier unsuccessful attempts
Earlier efforts to introduce Greek yoghurt to the US had failed:
• Dannon in 1942.
• Stonyfield in 1983.
The market was not ready for such an “exotic” product. By FAGE's arrival, growing numbers of health-conscious Americans created conditions for rapid growth (Warren, 2020).
Competitive pressure
FAGE's successful entry attracted intense competition, drawn by the category's high margins.
Its strongest competitor was Chobani, founded by Hamdi Ulukaya, a Turkish immigrant who came to the US to study in 1994.
Ulukaya wanted to recreate the rich, thick yoghurt of his childhood. Clever marketing and aggressive pricing helped Chobani win a 50% market share (Stanford & Boyle, 2010).
FAGE's response to competition
The arrival of major competitors
General Mills and Dannon, traditional US yoghurt leaders, were initially slow to enter Greek yoghurt. Once they recognised its potential, they launched products.
• Dannon launched Oikos with an aggressive promotional campaign.
• General Mills' Yoplait, a regular-yoghurt leader with approximately $1.4 billion in sales, introduced Greek yoghurt in 2010.
Both overtook FAGE, becoming the second- and third-largest US Greek yoghurt players (MarketLine, 2020a).
Other major companies and failed attempts
Several other large companies entered but withdrew when they found it difficult to secure profitable market share.
• Alpina, a global dairy business with over $800 million in revenue and operations in more than 20 countries, entered in 2012 but stopped a few years later.
• Kraft extended its Mediterranean brand Athenos into Greek yoghurt but withdrew because of low sales (Associated Press, 2012).
The role of private labels
Private labels also became important as Greek yoghurt entered the mainstream.
• Private labels are traditionally strong in dairy.
• Approximately 70% of milk and 37% of cheese are sold under private labels.
• They are also the largest sellers in regular yoghurt (Williams, 2020).
Many supermarket chains now produce private-label Greek yoghurt, capturing significant shares.
New trends: alternatives to Greek yoghurt
Greek yoghurt's popularity encouraged companies to introduce new yoghurt types. Although not direct competitors to FAGE, they slowed the category's growth.
• Icelandic yoghurt (skyr):
A strained yoghurt with fewer carbohydrates and high protein content.
• Australian and French yoghurt:
Thinner and closer to traditional American yoghurt, but with a creamy texture popular among consumers.
• Plant-based yoghurt:
Made from cashew, coconut, oat, almond or soya milk with yoghurt cultures.
• Popular among those avoiding dairy for personal, ethical or environmental reasons.
• Although its flavour is described as less refined than traditional yoghurt, growth is expected as taste improves and more people adopt plant-based diets (Warren, 2020).
FAGE's response
To protect its position and possibly regain leadership, FAGE launched several television campaigns.
• One successful 45-second advertisement used poetry to present yoghurt as an extraordinary sensory experience (Schultz and Parekh, 2011).
• Chobani also increased promotional spending across television, billboards, Twitter, Facebook and YouTube.
• Its campaign encouraged real consumers to share their experiences.
FAGE failed to retain its US share, particularly because large food companies such as General Mills and Dannon backed their brands with huge promotional campaigns.
FAGE's strategic dilemmas
A key question is whether FAGE can remain independent in the US or would be better selling its American operations to a multinational.
Pricing strategy:
• Greek yoghurt was traditionally more expensive because it requires substantial milk inputs (Nutrition Business Journal, 2007).
• A higher price was justified when it was a niche product.
• As a mainstream product with flattening sales, price becomes crucial for attracting new consumers.
• FAGE's high price may help explain its decline from 25% to around 5% share.
Which strategy should FAGE choose?
Given competitive uncertainty, it needs clear strategic choices:
1. Lower prices:
• Is cutting prices the right move?
• It could help regain share and discourage aggressive new entrants.
2. Higher prices and premium positioning:
• Should FAGE instead raise prices and position itself as the category's premium product?
• Its first-mover advantages and positive reputation as a Greek product could support this approach.
3. Promotional budget:
• How much should FAGE invest in marketing?
• Should it match competitors or concentrate on specific audiences?
4. Market diversification:
• Like Kraft's Athenos, FAGE could offer a broader Mediterranean range in the US.
• Surprisingly, despite being a significant cheese producer in Greece, it had never tried selling those products in the US.
5. Plant-based yoghurt:
• Given growing demand for plant-based dairy alternatives, FAGE could introduce plant-milk yoghurt.
• This could attract a new audience and reduce dependence on traditional dairy.
Conclusion
Whatever it chooses, intense competition means FAGE faces difficult decisions.
Its US story began with unexpected success, but strategic adjustments are inevitable if it is to remain relevant.
I then asked ChatGPT which strategy FAGE followed after 2015, the publication year I associated with the book. Its answer:
After 2015, FAGE pursued several initiatives to strengthen its US position:
1. Expanding production capacity:
To meet growing US demand, FAGE expanded its Johnstown facility. Work began in early 2013 and finished in the second half of 2017, taking annual capacity to 160,000 tonnes. The objective was to meet demand and optimise production costs.
2. Marketing and advertising investment:
In 2016, FAGE increased its media budget to $60 million, up 58% from 2015. Television campaigns aimed to raise awareness, including an international campaign under the slogan “nothing more. Never less.” It emphasised simplicity, versatility and premium quality across the US, UK, Italy and Greece.
3. Product diversification:
FAGE introduced Crossovers, combining Greek yoghurt with savoury additions: Olive Thyme with almonds, Tomato Basil with almonds, Coconut Curry with cashews and Carrot Ginger with pistachios. It sought consumers wanting less sweet options for different times of day.
4. Reviewing agency partnerships:
In 2017, after nearly seven years with MullenLowe, FAGE reviewed its advertising account. The agency handled creative, digital and social marketing, media planning and buying, brand strategy and PR as FAGE competed with Chobani. The review suggested a search for new strategies and perspectives.
These strategies aimed to increase FAGE's share of the competitive US Greek yoghurt market.
I then asked whether these interventions had increased share or produced other effects.
FAGE's post-2015 initiatives contributed to its continuing US performance. Although specific market-share figures were not disclosed, available information indicated positive trends:
1. Revenue growth:
In 2015, the US accounted for about 65% of FAGE revenue, up from 60% in 2014, highlighting the market's growing importance.
2. Profitability:
By mid-2022, operating performance remained solid, with positive market-share trends and high profitability.
3. Sales increase:
In the first quarter of 2023, FAGE reported US revenue growth of 9.7%, suggesting effective market strategies.
These results suggest capacity expansion, marketing and diversification helped maintain and potentially strengthen its competitive US position.
Finally, I asked ChatGPT to compare the revenue figures for 2015 and 2024:
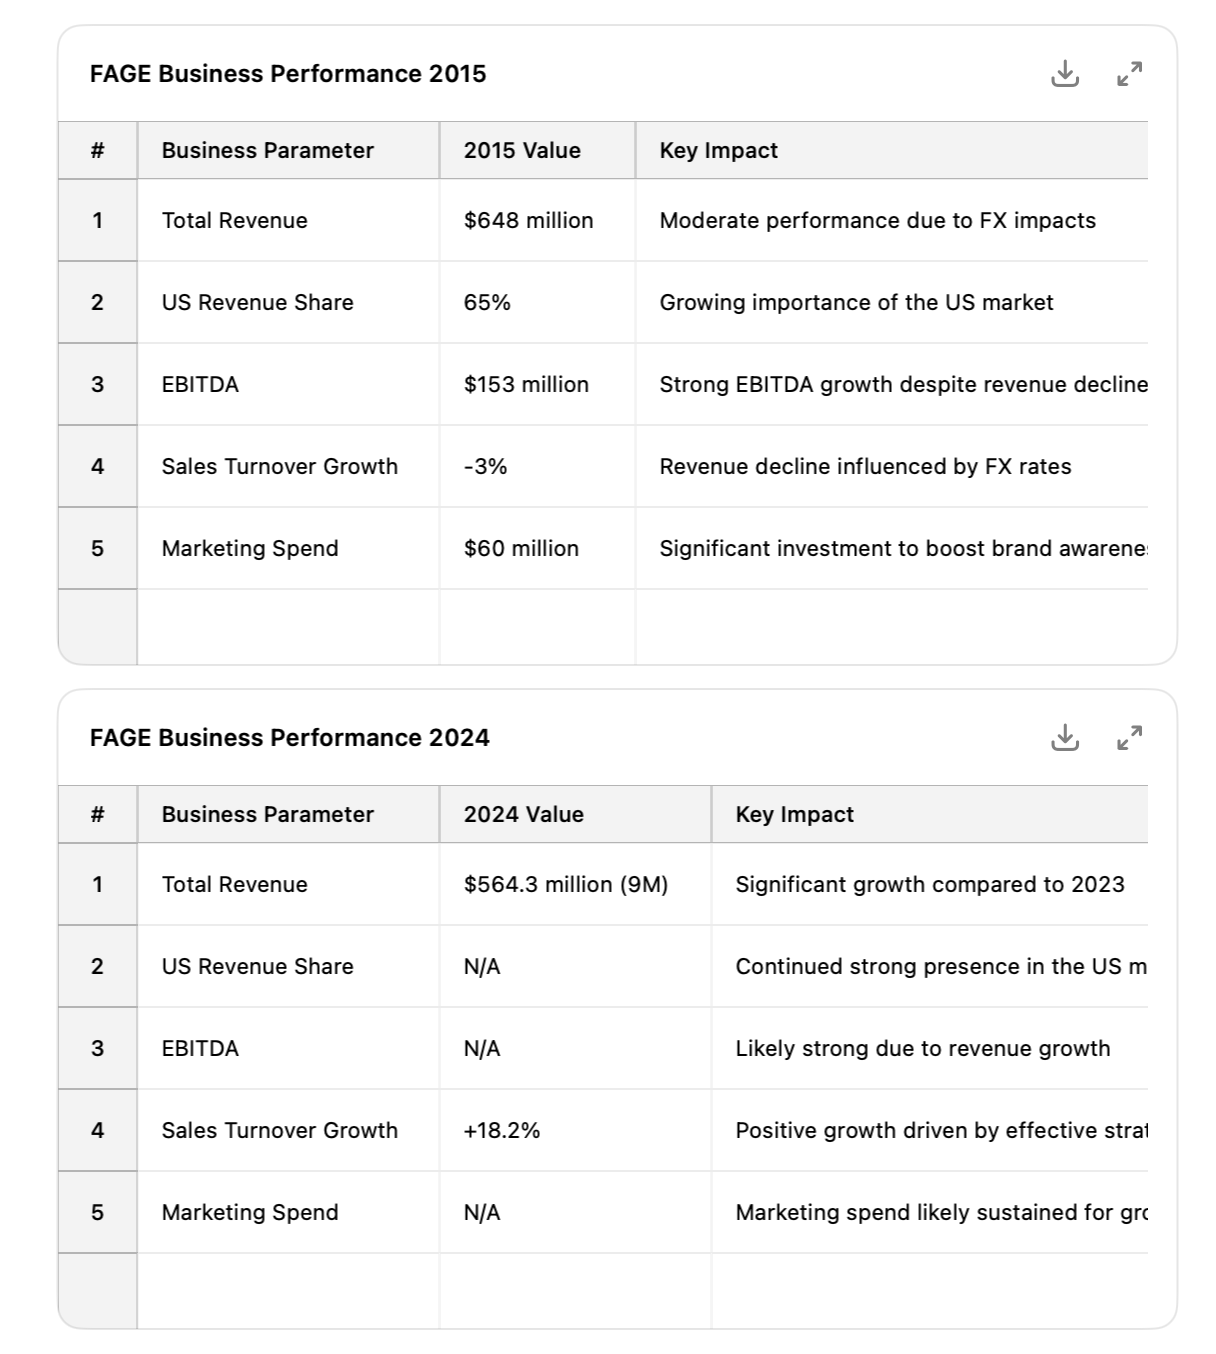
In 2015, FAGE International S.A. reported approximately $648 million in revenue, down 3% from the previous year, mainly because of exchange rates. EBITDA nevertheless rose by more than 50% to $153 million.
For the first nine months of 2024, FAGE reported revenue of $564.3 million, up 18.2% from $477.3 million in the corresponding 2023 period.
These figures suggest that, despite a slight decline in 2015, FAGE achieved significant growth in more recent years.
All well and good, but I was not particularly impressed, although COVID, referred to in the original article as 2019–2020, would certainly have affected plans. So I probed further.
ChatGPT: “Your observation is fair: despite substantial marketing and diversification investment, FAGE appears not to have achieved the expected US growth. Several factors could explain the disappointing results:
1. Greek yoghurt market saturation
• Saturation: rapid growth between 2010 and 2015 then flattened. Consumers had many alternatives and the novelty faded.
• Strong competition: Chobani and Danone's Oikos remained dominant. Chobani invested heavily in innovation, positioning and distribution, reinforcing its share.
2. Limited brand differentiation
• A less recognisable identity: FAGE's premium, authentic message was less compelling than Chobani's accessible, innovative positioning.
• Less attention to local trends: FAGE maintained a traditional, simple image while rivals responded faster to plant-based alternatives, lactose-free products and high-protein snacks.
3. Marketing strategy inefficiencies
• High spending, limited impact: substantially increased budgets, such as $60 million in 2016, did not translate into significant market growth. The message may have lacked appeal, or digital and social channels may have been underused.
• A traditional approach: FAGE continued television-led advertising while the market shifted towards digital and influencer campaigns, where Chobani and others performed better.
4. Limited innovation and diversification
• Crossovers were no game-changer: savoury yoghurt offered innovation, but the segment was too small to drive overall sales.
• Limited focus on growing niches: rivals targeted plant-based yoghurt, protein snacks and on-the-go products while FAGE stayed with classic yoghurt.
5. External economic factors
• Exchange-rate fluctuations: negative currency effects seen in 2015 may have recurred, given the company's international operations.
• Inflation and production costs: rising raw material, transport and manufacturing costs may have squeezed margins and complicated revenue growth despite higher volumes.
Conclusion
FAGE's investment in marketing, diversification and capacity was insufficient for lasting growth. The central problems appear to be:
• An overly traditional approach in a fast-changing market.
• Insufficient differentiation against aggressive competitors.
• Insufficient focus on emerging consumer trends.
FAGE might benefit from more radical repositioning or innovative categories better aligned with current demand…”
⇒ I see a lesson here for Belgian businesses that remain traditional, put little faith in sound marketing strategy and consequently grow slowly or stagnate. Perhaps they do not hire agencies, or choose the wrong ones to support their marketing?
There was also a brighter spot. I asked ChatGPT whether FAGE had pursued international expansion. Its answer:
ChatGPT: “Yes, FAGE took steps to expand internationally. Beyond the US, it strengthened European operations. In 2021, it announced a sustainable production facility in Hoogeveen, the Netherlands, with an initial investment exceeding €150 million. Expected to operate in 2024, the factory was intended to meet growing European demand.
This Dutch expansion underlines FAGE's strategy of strengthening its international position and presence beyond the United States.”
I have since noticed FAGE Greek yoghurt at Albert Heijn, Delhaize and Jumbo, among others.
In a future article, I will explore Lotus Bakeries' development and performance in recent years. Belgian businesses can learn a great deal from it.
English version of the BrandQs archive. Historical references are preserved.